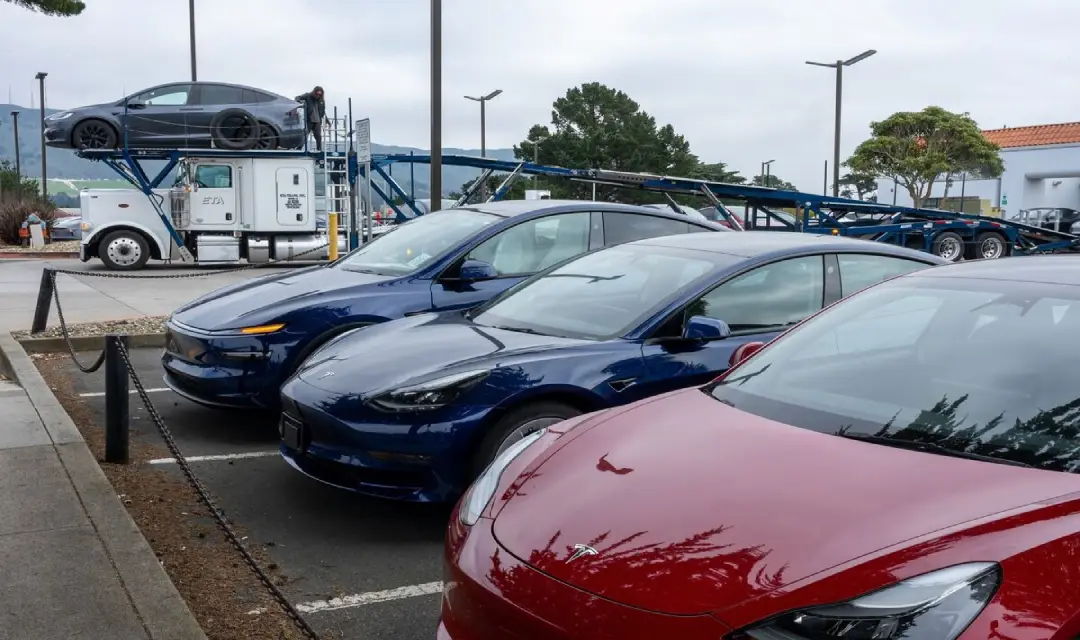
The U.S. vehicle market is experiencing a slowdown in 2026; through September, sales volume fell by 3.3% compared to the same period last year. Among the top 10 brands, Honda and Kia managed to buck this downward trend, posting significant gains, while Ford and Chevrolet saw declines. Tesla also experienced a downturn, with sales dropping by 22.7%.
Medium-term market trend
Following the 2008 financial crisis, the U.S. automotive market underwent a decade of steady recovery. Sales figures climbed from just 10.4 million units in 2009 to 16.5 million in 2014—an increase of 58.7%—and reached a decade high of 17.5 million units in 2017. Growing consumer confidence, stable fuel prices, and favorable financing conditions supported this growth; by 2017, sales volume was 68.3% higher than the 2009 low. Sales stabilized in 2018 and 2019, leaving the market at a high level as 2020 began. However, the COVID-19 pandemic interrupted this cycle. Factory closures, the shuttering of dealerships, and supply chain bottlenecks led to a 14% decline in sales in 2020, bringing the total to approximately 14.7 million units—a slump that wiped out much of the progress made since the previous crisis in the span of just one year. The 2021–2023 period was marked by high volatility: the market initially recovered, subsequently experienced a decline, and then stabilized once again. In 2021, sales reached 15.32 million units, though the recovery was tempered by limited vehicle availability resulting from semiconductor shortages. In 2022, the market contracted by 9.7% to 13.84 million units—a loss of 1.48 million vehicles that pushed sales volume even below the levels seen during the 2020 pandemic year.
This setback was driven by supply-side constraints rather than a lack of demand, a fact confirmed in 2023: sales rebounded by 12.0% to 15.50 million units—an increase of 1.67 million vehicles—surpassing the 2021 figure by 1.2%. While the market had absorbed the disruption within two years, it remained approximately 2.0 million units below the 2017 peak.
In 2024, sales rose by 2.8% to 15.94 million units, followed by a further increase of 2.1% to 16.26 million units in 2025. The market has thus grown for two consecutive years, though the rate of growth is slowing: from 432,715 additional vehicles in 2024 to 326,695 in 2025. Over the entire period, the volume is 6.1% higher than the 2021 figure—equating to an average annual growth rate of just 1.5%—and remains 7.1% below the 2017 peak. The market has stabilized in a phase of slow growth. High vehicle prices, increased financing costs, and rising maintenance expenses are keeping low- and middle-income consumers out of the market; consequently, further gains in sales are likely to be gradual.
The segment for battery electric vehicles (BEVs) and plug-in hybrids (PHEVs) has experienced a far more dramatic trajectory. Sales rose from just 109,567 units in 2014 (a 0.7% market share) to 430,592 units in 2021 (a 2.8% share). In 2022, the segment saw a sharp 71.5% increase to over 738,000 units, pushing its market share to 5.3%—all this during a year in which the overall market contracted by 9.7%. Improved technologies, the expansion of charging infrastructure, and government subsidies accelerated market penetration; by 2024, the volume reached 1.07 million units, representing a 6.7% market share. This marked the highest level to date. In 2025, sales fell by 12.8% to 930,490 units—a decline of more than 130,000 vehicles—and the market share dropped to 5.7%, even as the overall market grew by 2.1%. Reduced incentives, high purchase prices, more selective buying behavior, and intensified competition within the segment all contributed to this shift in trend. Nevertheless, the 2025 volume remains 116.1% higher than the figure for 2021, and the segment’s market share has doubled over the course of four years; electrification has thus become a permanent feature of the market structure. However, the upward trajectory is no longer a straight line: further growth now depends more on affordability and political support than on the initial momentum provided by "early adopters."
2026 outlook
Through September 2026 the market recorded 11,905,288 units, down 3.3% year-on-year. That equals 73.2% of the 16,261,785 units sold in all of 2025, leaving 4,356,497 vehicles to close the gap. The 2026 monthly average of 1,322,810 units is 2.4% below the 2025 average of 1,355,149. Matching the 2025 total would require about 1,452,166 units per month in the final quarter, a pace 9.8% above the year-to-date run rate. Momentum is reversing. Growth of 2.8% in 2024 and 2.1% in 2025 has turned into a 3.3% decline, the first contraction since 2022. Unless sales accelerate in the closing months, 2026 will end below the 2025 level and break a two-year run of annual gains.
The 2026 trend is a market losing ground under affordability pressure. Elevated prices, financing costs and ownership expenses are weighing most on lower- and middle-income buyers, and this softens demand across the board. Competition is intense and the results are polarized. Twelve of the twenty ranked brands are declining and eight are growing, and the gap between the best and worst performers is 55.9 percentage points. Twelve brands are outperforming the market, while eight are falling faster than the overall 3.3% decline. In a shrinking market, share gains come mainly from taking volume from competitors, so the contrast between winners and losers will probably widen. For the remainder of the year the outlook depends on whether the final quarter can lift sales well above the current pace. Otherwise the market is heading for a modest decline.
Brand performance
- Toyota -0.6%
- Ford -6.2%
- Chevrolet -5.0%
- Honda +8.9%
- Hyundai -0.6%
- Nissan +1.3%
- Kia +3.6%
- Subaru +0.5%
- GMC -1.6%
- Jeep -5.0%
- RAM +20.8%
- Tesla -22.7%
- Mazda -5.2%
- BMW +8.6%
- Lexus -3.2%
- Volkswagen -21.8%
- Mercedes -35.1%
- Buick -13.6%
- Acura +3.7%
- Chrysler +12.2%
The strongest performers are RAM (+20.8%) and Chrysler (+12.2%), followed by Honda (+8.9%) and BMW (+8.6%). RAM’s gain is the largest in the ranking and stands out against the 3.3% market decline. Acura (+3.7%), Kia (+3.6%), Nissan (+1.3%) and Subaru (+0.5%) also grew, if more modestly. Honda is the most significant gainer at scale, since it holds fourth place in the ranking and is adding volume in a falling market.
The market leaders are holding up better than their rivals. Toyota (-0.6%) and Hyundai (-0.6%) are almost flat, and GMC (-1.6%) is also outperforming the market. All three are gaining relative share even though their volumes are slipping. By contrast, several of the largest volume brands are losing ground faster than the market: Ford (-6.2%) and Chevrolet (-5.0%), ranked second and third, are both falling well below the overall rate, as is Jeep (-5.0%). Within the established U.S. nameplates the pattern is split, with RAM and Chrysler growing strongly while Ford, Chevrolet, Jeep and Buick decline. These points to brand-specific rather than category-wide drivers.
The weakest results are concentrated in a small group. Mercedes (-35.1%) records the steepest decline, followed by Tesla (-22.7%) and Volkswagen (-21.8%), all falling at roughly seven to ten times the market rate. Buick (-13.6%) is also well below the market, and Mazda (-5.2%) is slightly below it. The premium segment is divided. BMW and Acura are growing, Lexus (-3.2%) is roughly in line with the market, and Mercedes is contracting sharply. Competitively, the market is reshuffling around a few strong gainers and a group of brands that are losing share quickly, while the volume leaders are broadly stable.
BEV/PHEV Market Trend and Outlook
BEV/PHEV vehicles fell 32.6% year-on-year and account for 5.5% of the total industry, contracting nearly ten times faster than the overall market’s 3.3% decline. The pace of decline has accelerated sharply. The segment fell 12.8% in 2025 and is now falling at more than two and a half times that rate. The current share of 5.5% sits close to the 5.7% recorded across 2025 and below the 6.7% reached at the 2024 peak.
The segment’s trajectory has shifted from the surge of 2022 to a clear contraction. Between 2021 and 2024 BEV/PHEV volume grew from 430,592 units to 1.07 million units, and share rose from 2.8% to 6.7%. The decline that began in 2025 has deepened in 2026, so the segment is now giving back the gains of the expansion phase. The factors behind the reversal, reduced incentives, high purchase prices, greater consumer selectivity and increasing competition, appear to still be weighing on demand. The segment’s share is still meaningful, but it is no longer rising.
The implications for the wider industry are significant. A segment growing from a low base once supplied a large part of the market’s incremental volume, but it now acts as a drag on overall performance. Brands that built their strategies around rapid electrified growth face a more selective buyer, while brands with balanced portfolios are better placed to hold their position. The pace at which BEV/PHEV demand stabilizes will be a key factor in whether the wider market can return to growth.
BEV/PHEV brand performance
- Tesla -22.7%
- Lexus +15.9%
- Hyundai -28.1%
- Cadillac -13.6%
- Toyota +133.3%
- Rivian -15.8%
- Kia -14.8%
- Ford -58.7%
- Subaru +47.8%
- Honda -60.0%
Only three of the ten ranked brands are growing, and all three are Japanese: Toyota (+133.3%), Subaru (+47.8%) and Lexus (+15.9%). Toyota’s growth is the strongest in the ranking and runs against a segment that is contracting 32.6%. Subaru's increase is also large, and Lexus keeps a steadier, smaller gain. These brands are expanding while the segment shrinks, which means they are taking share.
Most of the other brands are declining, but several of them are falling more slowly than the segment. Tesla (-22.7%) leads the ranking and is declining at a slower pace than the segment, so it is holding its position. Hyundai (-28.1%), Rivian (-15.8%), Kia (-14.8%) and Cadillac (-13.6%) are all below the segment’s rate of decline. In total, eight of the ten ranked brands are outperforming the segment, so the steepest losses are concentrated in two names. Ford (-58.7%) and Honda (-60.0%) are both contracting at nearly twice the segment rate.
Comparing the BEV/PHEV ranking with the overall brand table shows brand-level contrasts. Honda is growing 8.9% overall but is down 60.0% in BEV/PHEV, and Kia is up 3.6% overall but down 14.8% in the segment. Ford is down 6.2% overall but falls 58.7% in BEV/PHEV, so electrified models are the main drag on its results. Toyota and Lexus show the opposite pattern, with electrified lines growing while their overall volumes are flat to declining. Tesla’s decline of 22.7% is identical in both rankings, which ties its overall result directly to the segment. The competitive picture is of a contracting segment in which a few brands are gaining share and the weakest electrified lineups are losing it rapidly.
Analysis and Outlook
The U.S. market's path divides into four phases. The first was a long post-crisis expansion, from 10.4 million units in 2009 to a peak of 17.5 million in 2017. The second was the 2020-2022 disruption, when the pandemic and supply constraints took volume down to 13.84 million units in 2022. The third was a recovery to 16.26 million units in 2025, with growth that slowed to 2.1%. The fourth, now under way, is a contraction: sales are down 3.3% through September at 11,905,288 units. The market has never regained its 2017 peak, and 2026 is moving it further from that level.
The central issue is affordability. High vehicle prices, elevated financing costs and rising ownership expenses are keeping lower- and middle-income consumers out of the market, which limits growth even when supply is available. This is a structural constraint rather than a temporary one, and it explains why recovery growth has faded from 12.0% in 2023 to 2.8%, 2.1% and now a decline. To match the 2025 total, the final quarter would need a pace 9.8% above the year-to-date average, which makes a return to annual growth in 2026 unlikely without a clear improvement in demand.
Competition has shifted from sharing growth to fighting for share. Twelve of twenty brands are declining, and the spread between RAM (+20.8%) and Mercedes (-35.1%) is 55.9 percentage points. The winners include RAM, Chrysler, Honda and BMW. Toyota and Hyundai are holding steady at the top, while Ford, Chevrolet, Jeep, Tesla, Volkswagen and Mercedes are losing ground. Scale offers limited protection, as the declines at Ford and Chevrolet, two of the three largest brands, show.
Electrification has moved from expansion to correction. BEV/PHEV vehicles reached 1.07 million units and a 6.7% share in 2024, fell 12.8% in 2025, and are down 32.6% in 2026 with a 5.5% share. Only Toyota, Subaru and Lexus are growing in the segment, while Honda and Ford are contracting far faster than the segment itself. Electrified products no longer guarantee growth. Portfolio balance and pricing are now decisive.
The strategic conclusions are clear. Manufacturers need pricing and financing structures that bring lower- and middle-income buyers back into a market that is still 7.1% below its peak. Brands should avoid relying on a single powertrain, because the brands with balanced portfolios are the ones holding volume. For the electrified segment, the key question is whether demand stabilizes at a share close to the current 5.5% or contracts further, and that will shape portfolio decisions across the industry. The final quarter of 2026 will show whether the market can recover enough ground to approach last year’s result.
Did you like our blog?
Comments (0)
All comments are reviewed and approved by an admin before appearing publicly.
No comments yet - be the first to share your thoughts.